
London’s luxury property market is facing mounting pressure as completed apartments in some of the city’s most expensive neighbourhoods remain unsold, leaving developers struggling with rising construction costs, expensive borrowing and weakening demand from wealthy buyers.
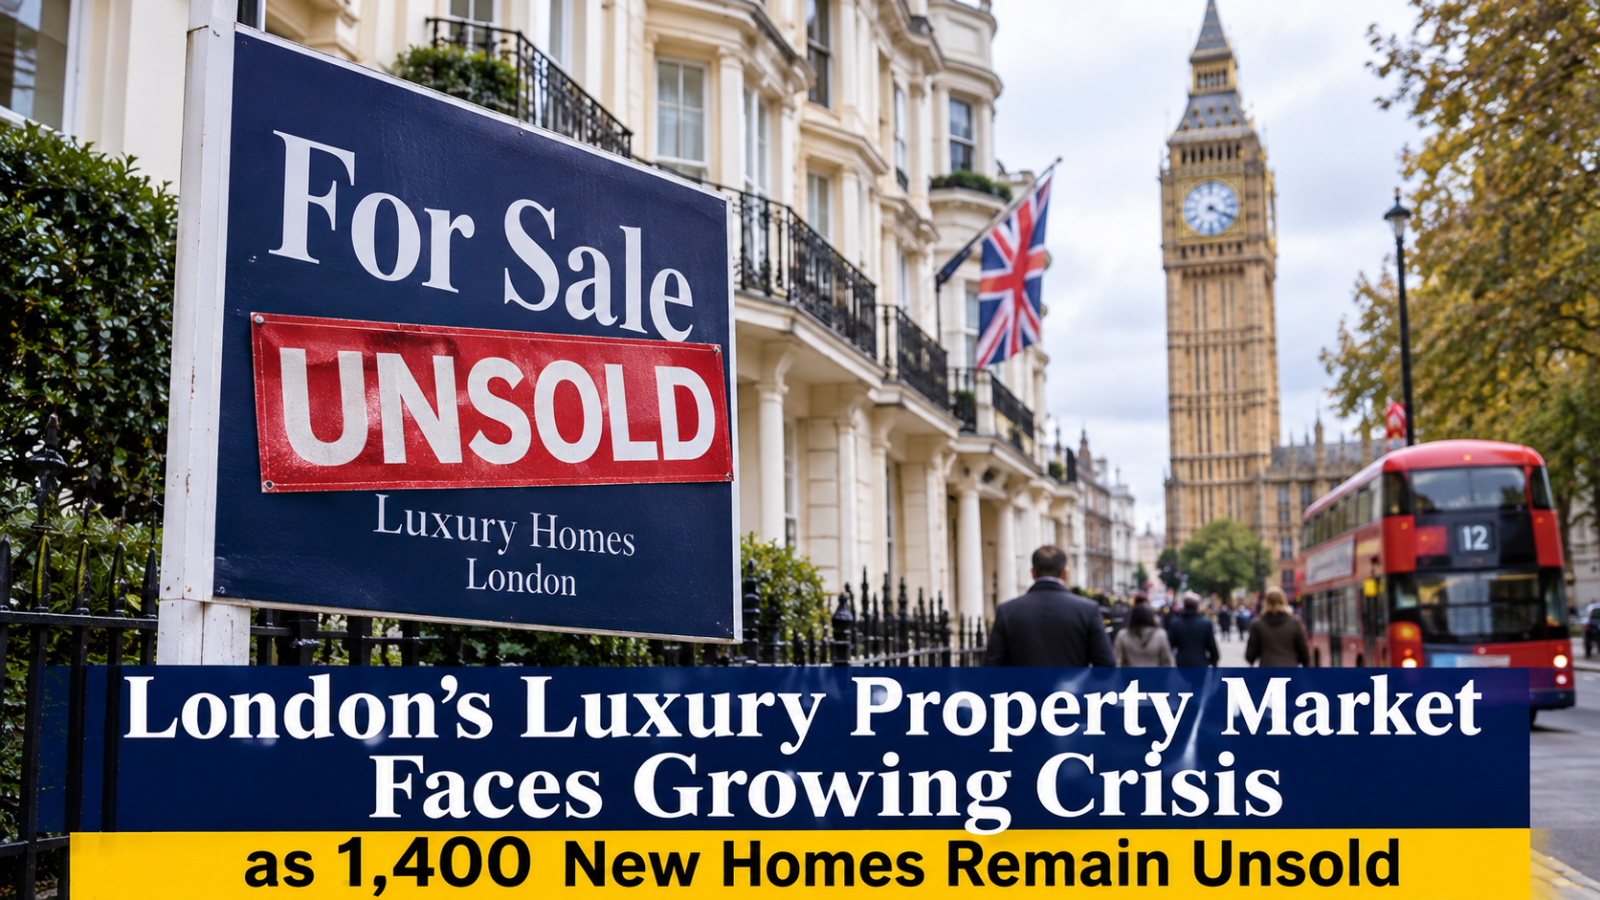
The scale of the problem is becoming increasingly difficult to ignore. By the end of September 2026, approximately 1,400 completed but unsold homes had accumulated in central London’s Zone 1, three times the number recorded in 2016.
The figures point to a growing imbalance in a market traditionally supported by wealthy domestic and international investors. Developers have continued to deliver expensive residential projects, but finding buyers willing to pay the asking prices has become more difficult.
The consequences extend beyond property sales. Companies are facing financial pressure from unsold developments, construction activity is slowing and creditors, including subcontractors, are being left with unpaid debts.
When Luxury Developments Become Financial Burdens
The slowdown is particularly visible in central London neighbourhoods such as Mayfair, Marylebone, Chelsea and Kensington, where developers have invested heavily in premium residential buildings.
These properties typically offer high-end facilities, including concierge services, luxury interiors and attractive city views. However, their selling prices place them beyond the reach of most London residents, making developers heavily dependent on a relatively small pool of wealthy buyers.
Market researcher Molior recorded only 1,600 housing construction starts in Zone 1 over the 12 months to September 2026, representing a 75 per cent decline compared with a decade earlier.
The contrast is significant: completed homes are accumulating while developers are becoming increasingly reluctant to begin new projects.
Rising construction costs and expensive financing have made the situation more difficult. Developers must continue servicing loans and meeting other financial obligations while waiting for buyers. The longer properties remain unsold, the greater the pressure on their cash flow.
Developers and Contractors Feel the Pressure
The difficulties have already contributed to financial distress among companies operating in London’s property sector.
London Richmond, a developer that focused on affluent residential neighbourhoods, entered administration in August 2026 after its owners ran out of funding.
The company had previously promoted a portfolio of 20 properties valued at more than £30 million. However, its collapse left more than 300 creditors waiting for payment, with approximately £39 million in outstanding debt reported by its administrator.
Ardmore Construction, which had been involved in major residential and hotel developments across London, also entered administration in 2025. Its construction business still owed more than £29 million to creditors and subcontractors as of September 2026, despite its parent group continuing to trade following a creditor agreement.
The pressure is not limited to smaller developers.
British Land announced in October that it would not proceed with the second phase of its Canada Water development amid rising costs and weak sales. Berkeley Group has also said it would stop purchasing new land, while rival housebuilder Taylor Wimpey has indicated plans to withdraw from London.
These developments demonstrate how a slowdown in property demand can spread through the construction supply chain, affecting contractors, suppliers, investors and workers.
Why Wealthy Buyers Are Holding Back
Several factors have weakened demand for London’s high-end properties.
Higher borrowing costs have made mortgage-financed purchases more expensive, while changes to property taxation have increased the cost of buying and holding certain properties.
Overseas investors, who have historically played an important role in London’s luxury housing market, have also become more cautious following changes to the UK’s tax treatment of non-domiciled residents and additional property purchases.
The uncertainty has encouraged some wealthy buyers to postpone purchases rather than commit millions of pounds to properties whose future costs and investment returns are less predictable.
Some are choosing to rent instead.
Property consultancy JLL recorded 338 homes with annual rents exceeding £150,000 being leased over the preceding 12 months, a 14 per cent increase from the previous year and a new record.
However, stronger rental activity does not necessarily solve developers’ financial problems. Rental income may provide an alternative to selling, but it does not automatically recover the capital invested in constructing expensive developments.
London’s Flat Prices Reveal a Deeper Problem
The pressure is also reflected in property prices.
Land Registry figures showed that the average London flat cost approximately £431,000 in June 2026, compared with about £433,000 in June 2016.
Although the nominal difference is relatively small, inflation means the property has lost considerable value in real terms over the decade.
The same comparison shows a wider difference between flats and houses, with London house prices increasing by approximately a fifth over the period.
The weakness in flat prices is particularly important because developers have invested heavily in apartment projects across central London.
It suggests that demand has not kept pace with the supply of certain types of residential property, even in locations traditionally associated with high-value real estate.
What the Slowdown Means for the Wider Economy
The problems facing London’s luxury property market highlight the risks associated with building developments around assumptions of continuously strong demand.
Property development requires substantial upfront capital, long construction periods and confidence that completed projects will attract buyers at prices capable of covering costs and generating returns.
When those assumptions weaken, developers can find themselves holding expensive assets that are difficult to sell while continuing to meet financing and operating expenses.
The slowdown also has implications for employment. Construction vacancies fell by 7,000 in the July-to-September quarter, according to estimates from the UK’s Office for National Statistics, making the sector the most affected across the country’s workforce.
London continues to face a substantial shortage of affordable housing, but the accumulation of unsold luxury apartments shows that the existence of housing demand does not mean every category of property will find buyers.
The distinction between housing need and effective purchasing demand is important. People may need homes, but that does not mean they can afford multimillion-pound apartments.
For developers, the immediate challenge is to adjust to a market in which wealthy buyers are more selective, financing is expensive and construction costs remain elevated.
The longer-term question is whether London’s property industry can better align new developments with actual demand.
The growing number of unsold apartments suggests that even the world’s most prestigious property markets are not immune to changing economic conditions. Luxury addresses and expensive finishes cannot guarantee sales when buyers are unwilling or unable to meet the price.


Leave a comment