
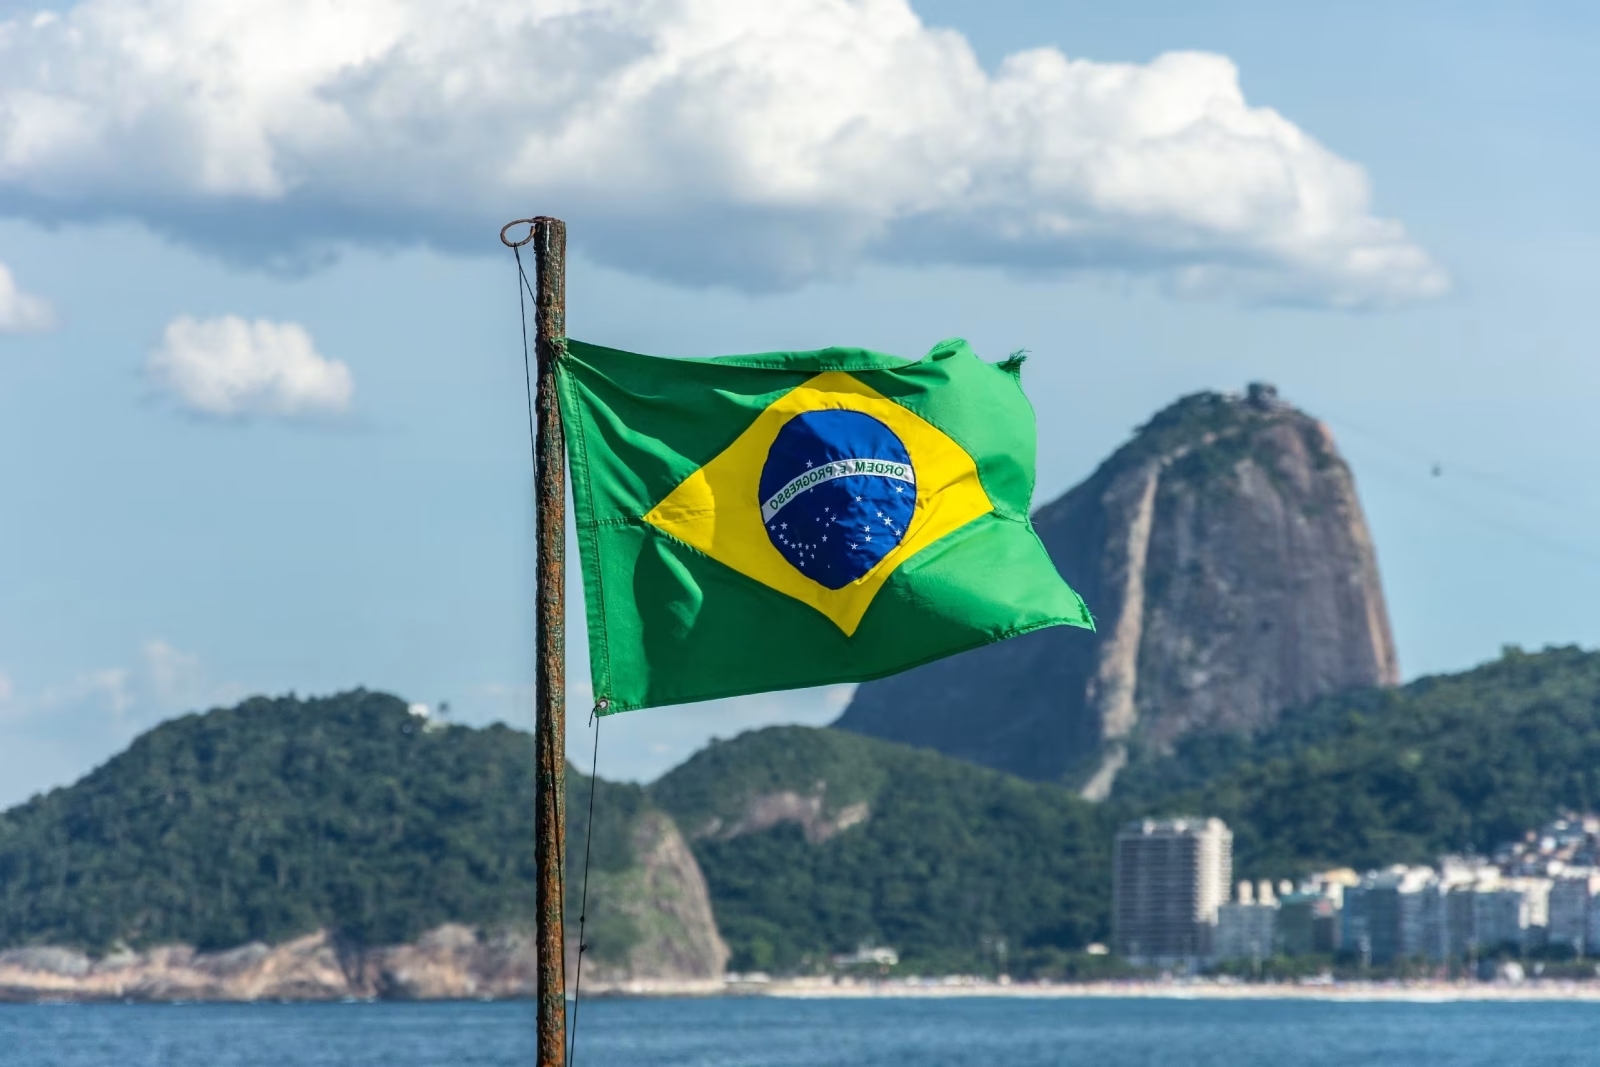
Brazil’s October presidential election is shaping up as another sharp contest between the political left and right, but investors see limited differences between President Luiz Inácio Lula da Silva and his main rival, Flávio Bolsonaro, when it comes to the country’s worsening fiscal outlook.
Flávio Bolsonaro, son of former far right President Jair Bolsonaro, has focused his campaign on Brazil’s economic difficulties as he seeks to unseat Lula, who currently holds a narrow lead in opinion polls.
Markets expect a Lula victory followed by measures that could slow the growth of public debt, but analysts remain doubtful that either candidate would be able to deliver the major fiscal reforms needed to put debt on a sustainable path.
According to Barclays economist Roberto Secemski, Brazil would need a fiscal adjustment equivalent to at least 2.5% of gross domestic product, or about 350 billion reais ($68 billion), to stabilize its debt by 2031.
Such an adjustment would be difficult because much of Brazil’s budget is tied to mandatory spending, while political divisions in Congress could make major reforms harder to pass.
Brazil’s nominal deficit averaged 8.6% of GDP between 2023 and 2025 and widened to 9.99% in the 12 months through June. Government debt reached 81.9% of GDP after rising by 3.3 percentage points in the first half of the year.
The 2026 budget classifies about 92% of primary spending as mandatory, leaving little room for cuts without changes to pensions, public sector wages, social benefits and spending rules.
Analysts at TS Lombard estimate that debt could peak at 94.7% of GDP in 2034 under a Lula-led reform scenario. Under Bolsonaro, they estimate debt could peak at about 90% in 2032 if his government pursued faster fiscal adjustment.
However, Bolsonaro has already abandoned some earlier proposals to loosen automatic spending increases after facing political resistance.
The election will also determine the composition of Congress, with voters choosing all 513 members of the lower house and 54 of the 81 senators. The result will be crucial to the next president’s ability to implement economic reforms.
Despite concerns about public finances, Brazil’s currency, the real, has strengthened about 5.8% against the dollar this year and nearly 20% since the end of 2024.
High interest rates have helped support the currency and attract investors, although they have also increased pressure on heavily indebted households and companies.
Economists warn that without stronger fiscal credibility, Brazil may struggle to reduce interest rates sustainably. An external economic shock could put additional pressure on the currency, businesses and households.
For investors, therefore, the key issue may be less about whether Lula or Bolsonaro wins and more about whether the next government can take credible action to slow the accumulation of debt.





Leave a comment