
The Central Bank of Nigeria (CBN) has unveiled a new framework to closely monitor foreign exchange transactions in the retail market, mandating the tracking of every dollar sold by Bureau De Change (BDC) operators.
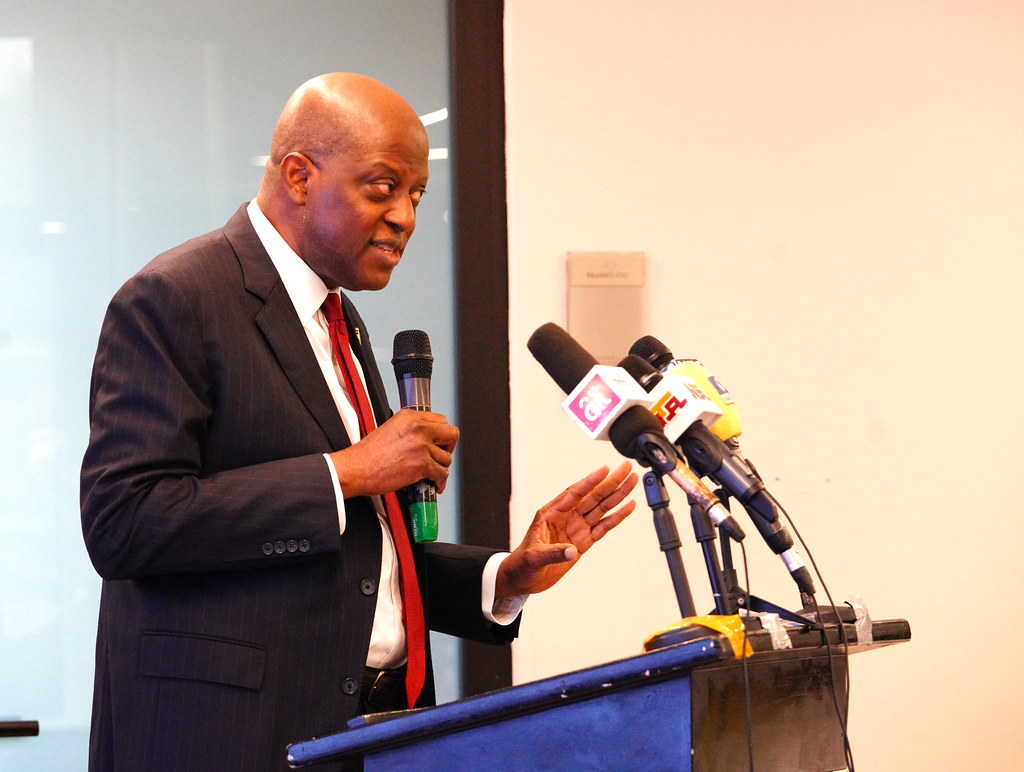
In operational guidelines dated July 15 and issued to banks and licensed BDCs, the apex bank announced the rollout of a centralised electronic platform designed to capture all foreign exchange purchases by BDCs from authorised dealer banks.
The platform, known as the FX BDC Purchase Tracker (FXBT), will require operators to submit transaction details in real time or within the same day, enabling the regulator to monitor activities across the market.
The initiative follows an earlier policy introduced in February, which allowed licensed BDCs to access foreign exchange directly from authorised banks through the Nigerian Foreign Exchange Market (NFEM) to improve liquidity.
With the new system, the CBN gains full visibility over each stage of transactions, from requests to approvals and final sales, allowing it to detect irregular practices such as exceeding purchase limits, sourcing funds from multiple banks, or diverting foreign exchange outside approved channels.
The move is part of broader efforts to enhance transparency and strengthen oversight in Nigeria’s retail foreign exchange segment, which has historically faced challenges around accountability.
Under the framework, authorised dealer banks are required to conduct strict Know-Your-Customer (KYC) checks and due diligence before processing foreign exchange requests for BDCs. Institutions that fail to meet these requirements will be denied access to forex sales.
Banks are also restricted from imposing exclusive arrangements on BDCs, ensuring operators retain the freedom to transact with any authorised dealer of their choice.
BDC operators must submit purchase requests through the digital portal, with banks expected to acknowledge such requests within two business hours and provide prompt confirmation or rejection.
The guidelines further require that any foreign exchange obtained and not utilised within the specified period must be returned to the market within 24 hours. Failure to comply could result in penalties, including forfeiture of funds and loss of access to official forex channels.
Additionally, all transactions must be conducted through registered bank accounts, with third-party dealings strictly prohibited to prevent abuse and ensure traceability.
The CBN said the measures are aimed at discouraging speculation, improving liquidity circulation and reinforcing compliance across the foreign exchange market.
The directive takes immediate effect, with all authorised banks and licensed BDC operators expected to comply fully with the new regulatory framework.
Source: TechCabal




Leave a comment