

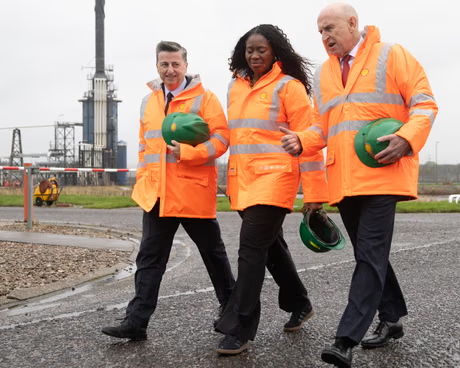
The United Kingdom is facing renewed economic pressure after annual inflation climbed to 3.5% in September, while government borrowing reached £24.5 billion, adding to the financial challenges facing Chancellor John Healey ahead of next week’s budget.
The latest inflation figure, reported by the Office for National Statistics (ONS), rose from 3.1% in August and exceeded economists’ expectations of 3.4%. Higher fuel prices were the biggest contributor, reflecting rising oil and gas costs linked to the conflict in the Middle East and disruptions to energy supplies through the Strait of Hormuz.
Petrol prices increased by 8.2 pence per litre in September, while diesel rose by 10.7 pence. Higher energy and transport costs are also expected to put further pressure on household budgets and food prices in the coming months.
The government’s public finances deteriorated as borrowing exceeded forecasts. Debt interest payments reached £10.9 billion in September, the highest figure for that month since records began. The ONS estimated that higher inflation added £4 billion to the bill.
The UK’s total public debt also reached an estimated £3 trillion, equivalent to 94% of gross domestic product. Borrowing for the financial year to date stood at £97.8 billion, £6 billion above the independent Office for Budget Responsibility’s forecast.
Healey blamed rising prices on conflicts in the Middle East and Europe, saying his budget would focus on economic growth and improving living standards.
See also Can Media Outlets Announce Results Before INEC’s Declaration? https://vistaonenews.com/2026/10/20/can-media-outlets-announce-results-before-inecs-declaration/
Economists warned that inflation could approach 4% by early 2027, raising expectations that the Bank of England could increase interest rates at its November meeting. However, some cautioned that higher rates would not resolve the underlying energy supply pressures and could weaken economic growth.







Leave a comment