
By Benson Daniel
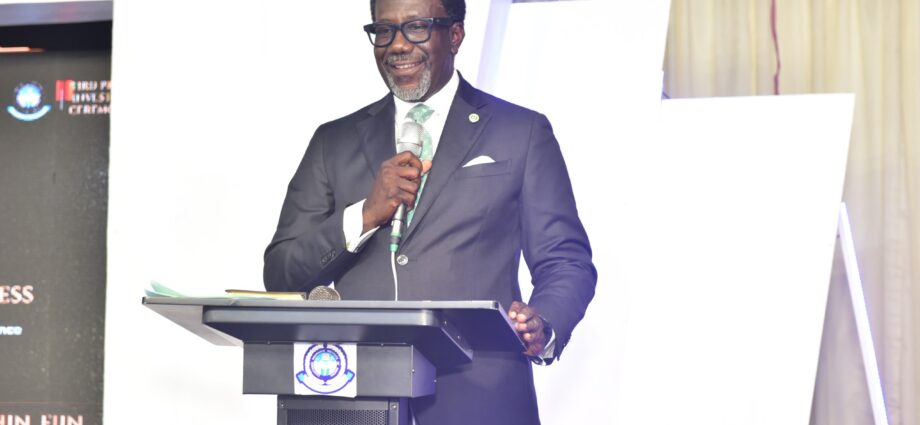
The National Insurance Commission (NAICOM) has warned insurance companies against failing to meet the July 31 recapitalisation deadline, stressing that no extension will be granted for compliance with the ongoing exercise.
The commission said insurers are expected to complete all necessary requirements to strengthen their capital base in line with regulatory directives aimed at improving the financial stability and resilience of the insurance industry.
NAICOM noted that the recapitalisation programme is designed to ensure operators maintain sufficient capital to meet policyholders’ obligations, absorb financial shocks and support the long-term growth of the sector.
The regulator cautioned that firms that fail to comply with the deadline risk facing regulatory sanctions, including restrictions on their operations and other measures permitted under existing insurance laws.
According to the commission, the exercise forms part of broader reforms to build a stronger and more competitive insurance industry capable of supporting economic development and attracting greater investor confidence.
Industry stakeholders have described the recapitalisation initiative as a critical step towards enhancing the capacity of insurance firms to underwrite larger risks, improve service delivery and increase public confidence in the sector.
NAICOM reiterated that it would continue to monitor compliance closely and ensure that all licensed operators adhere to the regulatory requirements within the stipulated timeframe.
The commission also encouraged insurance companies to maintain transparency throughout the process and engage with regulators where necessary to ensure a smooth transition.
With the July 31 deadline fast approaching, attention is now focused on how many insurers will successfully meet the new capital requirements, as the industry prepares for a new phase of regulatory oversight aimed at strengthening its financial foundation.




Leave a comment