
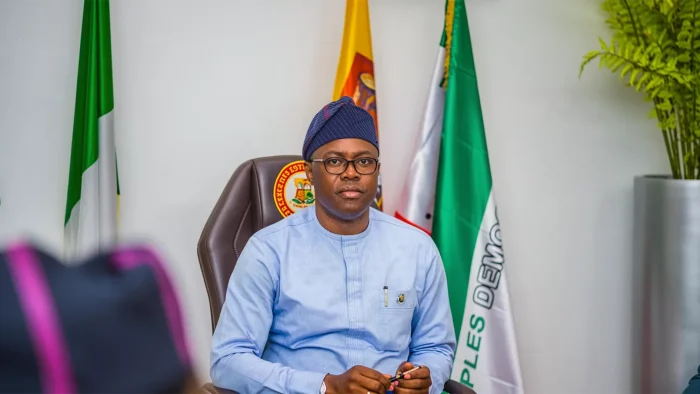
The Oyo State Government has rejected a report alleging that it spent N683.7 million to purchase two vehicles, describing the figure as a misinterpretation of the state’s audited financial records.
The disputed amount was linked to a 2004 Toyota Camry and a 10-seater Toyota Hiace bus. However, the state government said N683.7 million was not recorded as the purchase cost of the two vehicles.
The government explained that the N683.7 million figure appeared under a budget line titled “Advertisement and Publicity Awareness for the Public.” It said the allocation represented expenditure for a wider programme involving several activities and components, with the vehicles serving only as part of the programme’s logistics.
According to the government, the audited financial statement did not provide individual prices for the Toyota Camry and Hiace bus and did not assign the N683.7 million figure specifically to their procurement.
The state’s Special Adviser to the Governor on Media, Dr Sulaimon Olanrewaju, said it was therefore inaccurate to present the entire programme expenditure as the cost of two vehicles.
The government also pointed to other vehicle-related figures contained in the same financial records. These included N140 million for a 30-seater Toyota Coaster, N156.95 million for a 2021 Toyota Hiace Hummer bus, and N28.98 million and N50.71 million for Toyota Corolla vehicles from 2019/2020.
It argued that these entries did not support the allegation that N683.7 million was spent on a 2004 Toyota Camry and a 10-seater Toyota Hiace.
The controversy followed a report that interpreted the audited financial statement as showing that the Oyo State Government under Governor Seyi Makinde spent the amount on the two vehicles. The state government disputed that interpretation and said the financial document did not establish such a procurement cost.
The government urged media organisations and members of the public to examine financial documents carefully before drawing conclusions from individual budget lines. It said scrutiny of public spending was legitimate but should be based on an accurate reading of the records.
The administration also reaffirmed its stated commitment to transparency, accountability and responsible financial management, noting that its audited financial statements were prepared in accordance with statutory requirements.
The dispute highlights the importance of distinguishing between programme-level expenditure and the specific cost of individual assets when interpreting government financial statements.


Leave a comment