
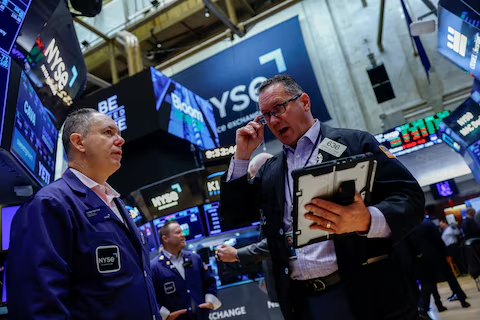
Systematic investment funds that adjust their stock holdings according to market volatility have built unusually large equity positions, raising the possibility that a relatively modest market shock could trigger significant selling.
Volatility-control funds increased their exposure as the S&P 500 climbed about 12% this year and market volatility fell. Their equity allocations are now around the 98th percentile of levels recorded since 2010, according to Deutsche Bank data.
The positioning means these funds have less room to increase stock purchases if markets continue rising, while a sharp increase in volatility could force them to reduce their equity holdings.
Estimates put assets managed by volatility-control strategies at between $300 billion and $500 billion. One model examined by Barclays suggests that a moderate deterioration in market conditions could result in more than $100 billion in equity selling as funds reduce their exposure.
Commodity Trading Advisers, another group of volatility-sensitive investment strategies, also have relatively high equity exposure, reaching the 82nd percentile historically.
The risk comes as the stock-market rally has become increasingly concentrated in technology companies, particularly those benefiting from heavy investment in artificial intelligence. Analysts say a sudden rise in volatility could therefore amplify selling as systematic funds respond to changing market conditions.
The developments add another layer of uncertainty to global markets following the sharp rise in government bond yields during the third quarter.



Leave a comment