
By Benson Daniel
Consumer credit in Nigeria declined by 20 per cent to ₦3.8 trillion, reflecting slower household borrowing amid high interest rates, persistent inflation and tightening lending conditions across the financial sector.
The decline underscores the challenges facing consumers as rising living costs continue to erode disposable income, making it more difficult for households to take on new loans or service existing debt. Financial institutions have also become more cautious in extending credit due to concerns over loan repayment risks and prevailing macroeconomic uncertainties.
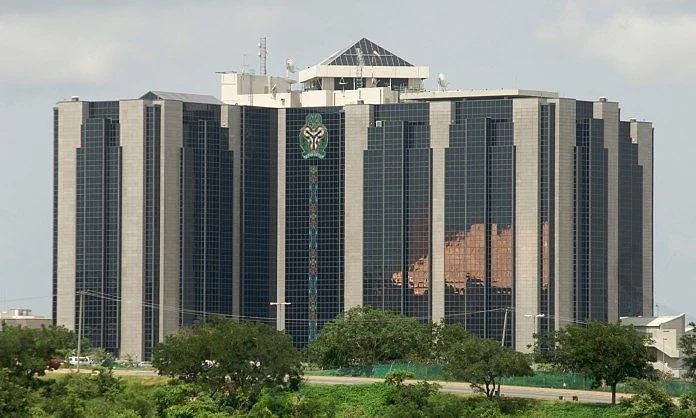
Analysts say the reduction in consumer credit is largely driven by the Central Bank of Nigeria’s tight monetary policy, which has pushed borrowing costs higher in an effort to curb inflation and stabilise the economy. The elevated interest rate environment has reduced demand for personal loans, mortgages and other retail credit facilities.
Banks have increasingly focused on improving asset quality and reducing exposure to high risk lending, leading to stricter credit assessment processes. While this approach has helped strengthen the resilience of the banking sector, it has also limited access to finance for many individuals and small businesses.
Economic experts note that weaker consumer borrowing could affect household spending, which remains a key driver of economic growth. Lower access to credit may reduce demand for goods and services, particularly in sectors such as retail, housing, automobiles and consumer electronics.
Despite the decline, industry observers believe consumer lending could gradually recover if inflation continues to moderate, interest rates ease and economic conditions improve. Ongoing efforts by the Federal Government and financial institutions to expand digital lending and financial inclusion are also expected to support broader access to credit over time.
The banking sector has continued to invest in technology driven lending platforms that simplify loan applications and improve credit assessment. These innovations are expected to strengthen consumer confidence and enhance financial inclusion once macroeconomic conditions become more favourable.
Market analysts say sustained economic reforms, exchange rate stability and improved employment opportunities will be critical to restoring consumer borrowing and supporting stronger domestic demand in the months ahead.



Leave a comment