
By Benson Daniel
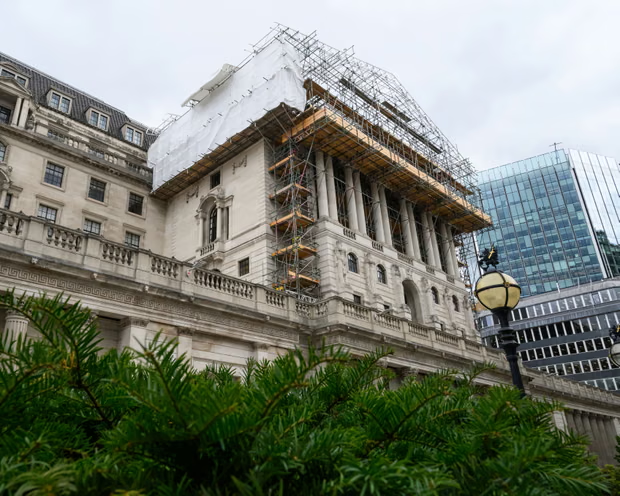
Economists are urging the Bank of England to slow or suspend its programme of selling government bonds, arguing that the policy is contributing to higher UK borrowing costs at a time when government finances are already under pressure.
The Bank is currently reducing its holdings of government bonds, known as gilts, as part of its quantitative-tightening programme. The process reverses some of the large-scale bond purchases made during the years of quantitative easing.
However, critics say continued active sales are adding to the supply of gilts in financial markets, putting upward pressure on bond yields and making it more expensive for the government to borrow.
The pressure comes as UK government borrowing costs have climbed sharply. The yield on 10-year government bonds has risen above 5.4%, its highest level since 2007, while the 30-year gilt yield has also reached levels not seen for decades.
Economists have therefore called on Chancellor John Healey to encourage the central bank to reconsider the pace of its bond sales ahead of this week’s Monetary Policy Committee meeting.
The Bank has already reduced the size of its gilt holdings substantially. Its bond portfolio, which peaked at around £875 billion, has fallen to below £490 billion as the quantitative-tightening programme has progressed.
The Bank reduced its annual target for reducing its gilt holdings from £100 billion to £70 billion last year. It is now widely expected to consider reducing the target further, potentially to about £50 billion.
Some analysts believe the Bank should go further and stop active sales altogether, allowing bonds to mature naturally rather than selling them directly into an already volatile market.
They argue that the approach could help ease pressure on government borrowing costs and reduce potential losses for taxpayers.
The Office for Budget Responsibility has estimated that the Bank’s bond sales could add around £47 billion to government debt by 2031 under assumptions involving continued active gilt sales.
The debate has become more urgent as global bond markets experience renewed volatility. Higher energy prices, persistent inflation concerns and expectations of tighter monetary policy internationally have pushed government bond yields higher across several major economies.
The Bank, however, maintains that Bank Rate remains its main monetary-policy tool and that quantitative tightening is being conducted with consideration for market conditions.
The central bank has also previously acknowledged that reducing its bond holdings can have a modest upward effect on long-term interest rates, while arguing that the process is necessary to reduce the size of its balance sheet and preserve flexibility for future interventions.
For the UK government, the issue is particularly important because higher gilt yields translate into greater debt-servicing costs. Rising interest payments could leave less room for public spending and increase pressure on the government ahead of its upcoming budget.
The Bank’s decision on the pace of quantitative tightening is therefore being closely watched by financial markets, with economists divided over whether continued bond sales are necessary or whether slowing the programme would provide relief to the Treasury without undermining monetary policy.



Leave a comment