
By Benson Daniel
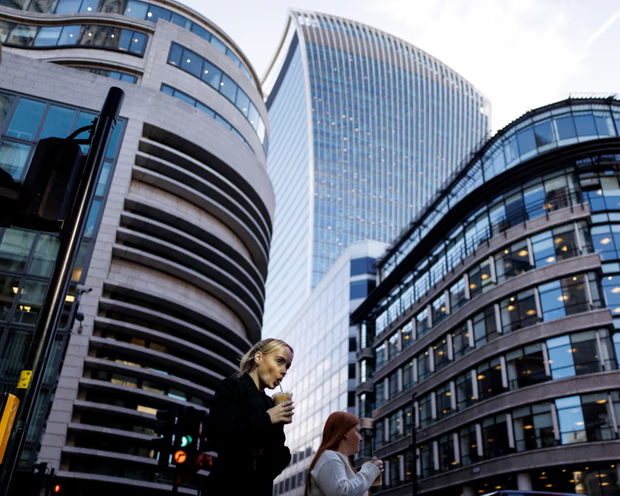
The cost of borrowing for the United Kingdom has climbed to its highest level in 18 years as a broad sell off in global bond markets intensified, adding pressure to the government’s finances ahead of its first budget under the new administration.
The yield on the benchmark 10 year gilt rose to 5.268 per cent on Wednesday, its highest level since June 2008. The increase followed a further rise of about four basis points on the day, after yields had already jumped 15 basis points in the previous session.
The surge reflects growing investor concern over inflation, government debt and the impact of higher energy prices on economies and central bank policy.
Rising oil prices have become a major source of concern for investors as the escalating conflict involving Iran threatens to keep energy costs elevated. Higher crude prices can feed directly into inflation by increasing transportation, production and household energy expenses.
The resulting uncertainty has encouraged investors to demand higher returns for holding long term government debt, pushing bond yields higher and prices lower.
The move in UK gilts is part of a wider global sell off that has also affected government bonds in the United States, Japan and major European economies.
For the British government, the rise comes at a particularly sensitive time. Higher gilt yields increase the cost of servicing public debt and could reduce the room available to finance spending plans while maintaining fiscal targets.
Finance Minister John Healey is preparing to present the government’s first budget on October 28, with the bond market now placing greater scrutiny on the government’s ability to manage borrowing and public finances.
Economists have warned that the increase in borrowing costs has significantly reduced the government’s fiscal headroom. Estimates indicate that the available margin could fall to about £13 billion from £23.6 billion previously.
That could leave the government facing difficult choices between raising additional revenue, reducing spending or accepting a narrower cushion against further economic shocks.
The pressure is not limited to government finances. Higher market interest rates can eventually translate into more expensive borrowing for households and businesses, particularly when banks and financial institutions adjust their lending rates.
Mortgage costs, corporate financing and investment decisions can all be affected when long term government bond yields rise sharply.
The five year gilt yield also climbed on Wednesday to 4.7534 per cent, its highest level since October 2023, highlighting the broad based nature of the pressure across the UK debt market.
Investors are increasingly concerned that the combination of elevated oil prices and persistent inflation could make it harder for central banks to ease monetary policy.
That prospect has added to pressure across bond markets, as investors reassess the outlook for interest rates and demand greater compensation for inflation and fiscal risks.
The developments also underline the sensitivity of heavily indebted governments to changes in global financial conditions. A sustained rise in borrowing costs could increase debt servicing obligations and make it more difficult for policymakers to respond to economic downturns.
For the UK government, attention will now turn to whether the bond market stabilises before the October budget or whether borrowing costs continue to rise.
Any further increase could intensify pressure on the government to demonstrate fiscal discipline and provide investors with confidence that public finances remain under control.






Leave a comment